The browser you are using is not supported. Please consider using a modern browser.

Article
Your Bank Bought the Analytics. Now What?
 •
Oct 23, 2026
When I was a bank CFO, I spent considerable time evaluating technology investments, building business cases, and determining whether the anticipated return justified the expense. There was always a great deal of attention given to what a new system or platform could do for the bank, how much it would cost, and what it would take to implement it.
But there’s another question that deserves just as much attention. What happens after the technology is implemented? Because the value of any investment ultimately depends on whether it changes how people work, how decisions get made, and what the institution is able to accomplish.
For community banks investing in analytics and broader data capabilities, the real challenge comes after the information is available. Making that information part of how the institution operates takes trusted data, a willingness to change established processes, and leadership that stays engaged long after implementation.
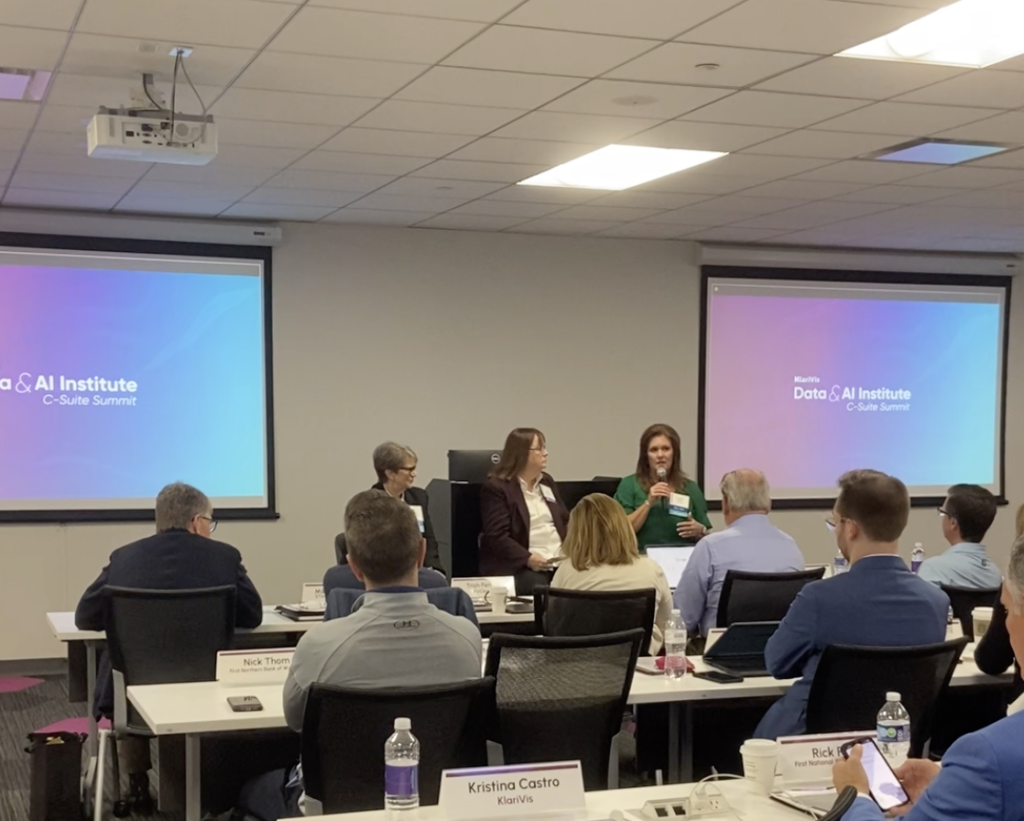
That was the focus of a conversation at our recent KlariVis Data & AI Institute C-Suite Summit in Roanoke, where Gill Hundley, KlariVis’ Chief Operating and Risk Officer, moderated a discussion with Susan Hubble, EVP and Chief Information Officer at Peoples Security Bank & Trust, and Cynthia Cain, EVP and Chief Operating Officer at SmartBank. Both institutions have been using KlariVis for several years, and both executives shared candid perspectives on what has worked, what hasn’t, and what they would do differently.
One of my favorite moments came when Gill asked Cynthia what success looked like when SmartBank first implemented KlariVis. She answered, “People asking us questions.”
I loved that response because it gets to the heart of what makes data valuable. When bankers begin questioning what they’re seeing, looking more closely at their portfolios, and asking why something has changed, they’re engaging with their business differently. Rather than waiting for someone to deliver a report, they’re exploring the information themselves, challenging assumptions, and developing a deeper understanding of what’s happening within their institution.
And that is where meaningful change begins.
Leadership sets the expectation for data-driven decision making
One of the clearest lessons from both executives was the influence leadership has on whether technology becomes part of how a bank operates.
At SmartBank, senior executives regularly use KlariVis to understand performance and guide conversations with their teams. The chief financial officer, chief credit officer, divisional presidents, and other leaders access the platform routinely, and data is part of the bank’s Monday morning meetings. Cynthia explained that when leaders are looking at the numbers and asking questions, the people reporting to them begin doing the same.
Susan described a similar turning point at Peoples Security. After an initial period of adoption, usage slowed as the bank worked through a merger and competing priorities. She made a point of getting the chief banking officer more involved, and his use of the platform began influencing the teams around him.
Questions about significant deposit movements that previously required someone to research the answer could now be addressed during leadership meetings. The bank also began using the information to evaluate deposit pricing strategies and identify opportunities to deepen customer relationships.
At SmartBank, leadership uses daily visibility into deposit activity, funding needs, and rate changes to inform business decisions. In both cases, information has become part of how the bank manages its business rather than a tool employees occasionally open.
Think about the difference that makes. Rather than leaving a meeting with a list of questions for someone to research, leaders can explore what’s happening while the conversation is taking place. They can challenge assumptions, identify opportunities, and make more informed decisions.
When executives consistently use data to manage their business, they establish expectations that extend throughout the organization. The technology stops being one more resource available to employees and becomes part of how the institution operates.
Better decisions start with better bank data management
Another important theme was the relationship between adoption and confidence in the information.
Cynthia, who spent much of her career in accounting and finance, emphasized the importance of reconciliation and controls. At SmartBank, where data is used extensively throughout the institution, the team needs confidence that the information is accurate and that processes are in place to identify and resolve discrepancies.
Susan shared an experience that many bankers will recognize. A market president questioned why a new lender’s loans weren’t appearing correctly in KlariVis. After investigating, the issue turned out to be how the officer information had been assigned in the bank’s core system. The platform was reflecting the underlying data, but the increased visibility exposed an issue that needed attention.
I’ve seen this happen again and again. When information becomes more accessible across an institution, inconsistencies that may have existed for years suddenly become visible. Officer assignments, transaction codes, and other data elements take on greater importance because people are relying on that information to understand performance and make decisions.
Data governance shows up in exactly those details. The information people depend on has to be accurate, consistently defined, and backed by clear accountability across the institution.
Those discoveries can be uncomfortable, particularly when employees are accustomed to trusting reports they’ve used for years. But they’re also opportunities to improve the quality of the information the bank depends on.
Better visibility helps bankers understand their business, and it also reveals where underlying data and processes need attention, strengthening the foundation for better decisions. That foundation matters even more as banks begin putting AI to work. AI can accelerate analysis and uncover opportunities, but it doesn’t make inaccurate or inconsistent data trustworthy. Without that foundation, banks risk using powerful new technology to amplify the very problems they’re trying to solve.
New technology, old habits
One pattern comes up again and again. Banks invest in new technology because they want to improve how they operate, then spend much of the implementation trying to make the new technology work exactly like the old system. The same reports, the same workflows, the same processes, often without anyone stopping to ask whether those processes still make sense.
Some of those requirements serve important operational or regulatory purposes. Others exist simply because that’s how things have always been done. When the focus becomes recreating everything that existed before, banks risk carrying the same inefficiencies into a new investment. The technology may have changed, but the way the institution operates hasn’t.
Susan’s experience at Peoples Security illustrates how difficult it can be to move beyond established practices. She described how years of accumulated reporting had created multiple versions of essentially the same information, often differing only in how the data was sorted or who received it. Even after implementing KlariVis, many of those reports continued to run. Looking back, she said she would have turned them off “a whole lot faster than I did.”
I suspect most bank executives can relate. Employees become comfortable with familiar reports and processes, and even when better information is available, there’s a natural tendency to continue doing what has always been done.
Cynthia offered an approach I particularly liked. At SmartBank, employees who prefer spreadsheets can still use them. They’re simply pulling the information from KlariVis rather than relying on separately produced reports delivered to their inboxes.
The objective is consistent, reliable information for everyone, with far less of the unnecessary work and confusion that come from maintaining multiple reporting processes. How each banker chooses to work with that information matters much less.
Both executives also emphasized the importance of engaging employees early. SmartBank involved power users of existing systems before the contract was signed, building support among people who understood the challenges firsthand. Susan acknowledged that she would bring more employees into the process earlier, encouraging banks to find enthusiastic users who could “overwhelm the doubters with their excitement.”
Employees are often more receptive to change when they see colleagues they trust solving familiar problems a different way. That initial enthusiasm needs continued support, though, particularly as the organization evolves.
A leader’s role doesn’t end at go-live
This is one of the areas where I’ve seen the greatest difference between institutions that realize meaningful value from their technology investments and those where progress stalls.
Banks are accustomed to managing implementations as projects, with timelines, milestones, assigned responsibilities, and a defined go-live date. That structure is necessary to get technology up and running. The problem comes when the institution continues to treat the investment as a completed project rather than an ongoing change in how the business operates.
Too often, the executive who sponsored the investment moves on to the next priority once implementation is complete. Responsibility shifts to a department or individual managing the platform, and the broader effort to change how people work begins to lose momentum.
I’ve seen this happen enough times to believe that continued executive sponsorship is one of the most important factors in long-term success. The executive who supported the investment needs to stay engaged well beyond the day-to-day activities, making sure the institution is realizing the value it set out to achieve.
That means continuing to ask how the technology is being used, what decisions it’s helping inform, and where additional opportunities exist. It means challenging established processes when they no longer make sense and holding leaders across the institution accountable for making the most of the investment.
Susan’s experience at Peoples Security illustrates this well. Getting the chief banking officer actively involved helped move adoption forward because he used the platform himself, brought the information into his meetings, and showed his team how it supported decisions the bank needed to make.
Cynthia also emphasized the importance of having someone accountable for the platform’s ongoing success. That responsibility, she said, “can’t be an add on to someone else’s job.” At SmartBank, day-to-day ownership has evolved as the organization has grown, but executive engagement has remained an important part of how the bank drives adoption.
Those are two distinct responsibilities, and both matter. Someone needs to manage the platform, coordinate training, support users, and help departments get the most from the information. But operational ownership cannot replace executive leadership. Without continued engagement from the top, even a well-managed platform can struggle to become embedded in how the institution operates.
Both banks have worked through mergers, system conversions, employee changes, and evolving business priorities. Each creates new opportunities to expand how data is used, along with the need for continued training and engagement. Both executives also spoke about the importance of maintaining a close relationship with their KlariVis client success teams as those needs evolve.
That ongoing partnership matters. The bank has a responsibility to lead the organizational change, and its technology partner has a responsibility to continue helping the institution realize value from the investment.
Implementation can be managed as a project, but realizing the value of that investment requires an ongoing commitment from leadership.
The real ROI comes from changing how people work
What I appreciated most about Susan’s and Cynthia’s perspectives was their willingness to acknowledge that the work isn’t finished. Both institutions have made real progress, but they continue to identify opportunities to engage more employees, improve processes, and expand how information is used.
As a former CFO, I understand the importance of demonstrating a return on technology investments. Community banks have to be thoughtful about where they allocate resources, and every investment needs to contribute real value.
But the return can’t be measured solely by what the technology is capable of doing or whether implementation was completed on time. The more important measure is what the institution can accomplish because of it.
Are employees spending less time gathering information and more time understanding it? Are leaders identifying opportunities and potential challenges sooner? Is the institution making better decisions about pricing, growth, and customer relationships? Do teams have the visibility they need to take greater ownership of their results?
Those are the questions bank executives should continue asking long after implementation is complete.
For community banks, the opportunity comes from using information to make better decisions, spot opportunities earlier, and manage their institutions more effectively. Access alone does not get you there. It takes leaders who set clear expectations, encourage their teams to challenge the way things have always been done, and make using data part of how the bank operates every day.
Buying the analytics is an investment in what your bank could accomplish. Turning that investment into measurable business value is a leadership responsibility, and the work doesn’t end when the technology goes live.