The browser you are using is not supported. Please consider using a modern browser.

Article
Core Modernization Is Really Business Modernization
 •
Oct 2, 2026
I spent an hour this week at the CCBN Executive Innovation Forum with my good friend Tom Sa talking about core modernization. But pretty early in the conversation, it became clear that what we were really talking about was something much bigger.
Business modernization.
For years, banks have tended to frame modernization around the core. Are we on the right one? Should we convert? Should we stay? What does the next renewal look like?
Those are fair questions, but I’m not convinced they are the most important ones anymore.
The better place to start is with the business.
What are we trying to become? Where are we creating unnecessary friction for employees or customers? Where are we too slow? What information do our people need that they cannot easily get today? What capabilities will the bank need three or five years from now that we may not even be thinking about yet?
Once you start there, the role of the core looks different.
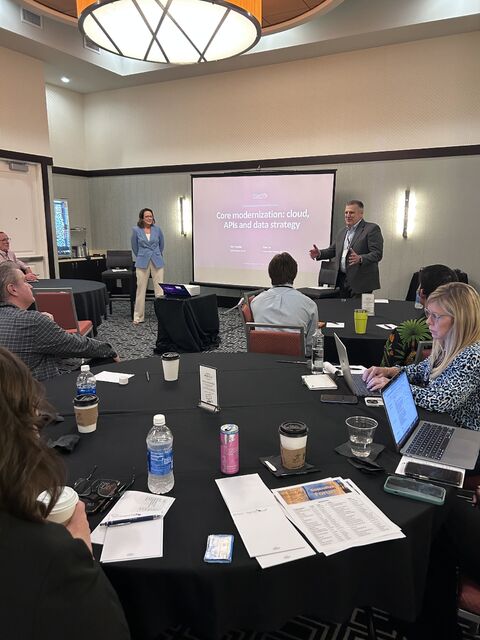
Tom and I have both lived through core evaluations and conversions. In one of his banks, he pushed the team to evaluate another core because there was real frustration with the existing provider. They went through the process, saw all the capabilities the other provider had to offer and started asking whether a conversion made sense.
Then he stepped back and realized the core itself was not really what they were shopping for. What they wanted were the capabilities around it.
That resonated with me because I have lived a version of that too. I remember going through a core conversion as a banker and hearing all kinds of functionality that was coming. Some of it was still coming years later.
It changes the questions I think banks should be asking.
Not simply, “Does my, or will my, provider have this?”
When do they say it will be available? How specific are they willing to be about that timeframe? What is their track record of delivering what they said they would deliver, when they said they would deliver it? And are customers actually using the capabilities they have already brought to market?
There is nothing inherently wrong with a capability taking six months to build. Some things should take time to build well. The bigger issue is whether you can trust the roadmap enough to make business decisions around it.
Speed matters. But if you are making strategic decisions around a provider’s roadmap, their ability to deliver when they say they will matters just as much.
A bank can no longer build its technology strategy around the assumption that one provider will anticipate and deliver everything it is going to need. Customer expectations are moving too quickly. Payments are changing. AI is changing what is possible. The amount of data available to banks continues to grow. The tools employees use in every other part of their lives are changing what they expect at work.
The question is not whether the core is important. Of course it is.
The question is how much of the bank’s ability to move do you want dependent on it.
That is where business modernization starts to become a very different conversation from core modernization.
It means thinking about the technology stack as a whole. What should come from the core provider? Where does best of breed make more sense? How easily can you integrate another partner? How much control do you have over your own data? And just as importantly, has the bank built the internal discipline to manage a more flexible environment?
One thing we did not spend enough time on is governance.
And I don’t mean governance as another committee, another policy or another layer of bureaucracy.
I mean having enough structure around technology decisions that the bank can actually move with confidence.
If we want a more open technology environment, if we want to work with more specialized partners, if we want to bring AI into the organization, then somebody has to establish the rules of the road.
How do we decide which business problems are worth solving? Who owns the outcome? Who evaluates the risk? What are our requirements around data access and security? How will a new solution fit with the rest of the technology stack? And once we buy it, who is accountable for making sure we actually use it?
Without that structure, modernization can quickly turn into a collection of disconnected technology projects.
That is not modernization. It is just more technology.
Good governance should do the opposite. It should give people a framework to make better decisions faster because every new idea does not start from scratch.
The same thinking applies to APIs.
Nearly everybody says they have them now. That alone does not tell me much.
Can I read the data? Can I write to the system? What does the contract allow? Are there limits? What will it cost? Who is responsible for the integration? And when I need something, who decides how high my request sits on the priority list?
One connection solves one problem. Having a consistent approach to connectivity gives the bank a way to keep solving problems as the business changes.
And then there is the piece I believe sits underneath all of this: data.
You can modernize digital banking. You can change your loan origination system. You can add new payment capabilities. You can bring in AI.
But if the bank still cannot easily access, understand and use its own data, I would argue you have not really modernized much at all.
That is why I think data ownership and data access have to become part of every technology discussion, not something we think about later.
The bank’s data belongs to the bank. But that does not always mean the bank can easily get to it.
The time to figure that out is not when you are trying to leave a vendor. It is when you are negotiating the agreement.
How do we retrieve our data? In what format? How often? Is there a cost? Can another provider access it? What happens when the relationship ends?
Those may not feel like the most exciting questions when everyone is focused on the new technology, but they may be some of the most important questions you ask. Especially now.
We hear banks talking about AI everywhere we go. I am excited about what AI can do for this industry too. But there is no AI strategy without a data strategy underneath it. And there is not much of a data strategy if your information is scattered across systems you cannot easily access or trust.
That brings me back to the business.
One of my favorite parts of the conversation came from Tom, which probably will not surprise anyone who knows he is a former CFO.
We were talking about technology negotiations and how quickly they become cost exercises. How much can we save? How much can we negotiate out of the contract? How do we prove the ROI?
Those things matter. Banks have to be good stewards of their resources.
But Tom made the point that maybe the goal should not always be to spend less.
Maybe the better question is, what more can we get for the dollars we are already spending?
That is a very different conversation.
Can we give our people better information? Can we eliminate work that adds no value? Can we make decisions faster? Can we see customer relationships more clearly? Can we create a better experience? Can we give our teams the capacity to do more without simply adding more people?
Those are business outcomes.
And that is ultimately why I think we need to change the language around modernization.
A modern bank is not a bank with the newest core.
It is a bank that can adapt.
It has access to its data. Its people have the information they need to make good decisions. Its technology does not box it in. There is enough governance around technology and data that the bank can move without creating unnecessary risk. And its leadership team understands what it is trying to accomplish before it starts buying tools.
So when the next major technology contract comes up for renewal, I would spend less time starting with, “What should we replace?”
Start with the business instead.
What does our bank need to be able to do that we cannot do today?